Beyond Revenue: Nigeria’s $1 Trillion Dream Rests on Business Growth, Not Just Taxes
Nigeria’s goal of hitting a $1 trillion economy by 2030 hinges less on how much tax the government collects and more on whether its policies actually help businesses expand, attract investment, and create jobs.
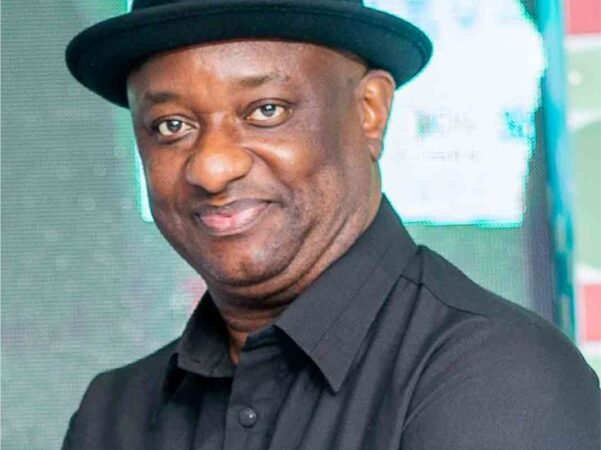
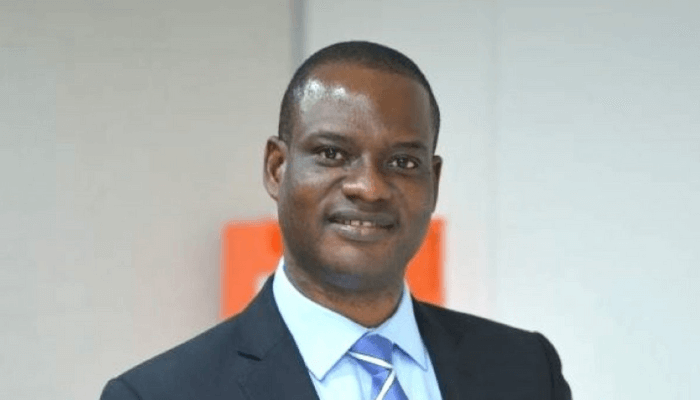
That was the key takeaway from Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, at the 2026 Finance and Business Online Publishers Association (FiBOP) Conference and Awards in Lagos.
Represented by his Special Adviser on Revenue, Olufemi Olarinde, Oyedele explained that the government’s new tax policy is built to fuel economic growth, improve living standards, and create an environment where businesses and citizens can thrive.
At the core of the reforms is a simple idea: “Tax prosperity, not poverty. Tax the few, not the citizens.”
The message marks a shift away from focusing solely on revenue collection toward building an economy that generates sustainable wealth and expands opportunity.
Speaking on the theme “The New Tax Policy and Its Role in Accelerating the $1 Trillion Economy Target by 2030,” Oyedele argued that Nigeria’s economic ambition should be measured by more than GDP. For ordinary Nigerians, the real test is whether businesses grow, incomes rise, jobs become easier to find, and living conditions improve.
Oyedele stressed that an entrepreneur who gets the right support today could become a major employer tomorrow. A tax system that burdens businesses, he warned, could actually undermine the growth needed to expand the revenue base.
He said the government is working to better align monetary policy with tax administration—including matching tax-related interest and penalty rates with prevailing economic conditions while keeping consequences for non-compliance.
The goal is to cut unnecessary costs, improve access to capital, and encourage businesses to invest, expand, and hire more Nigerians.
Still, Oyedele acknowledged that tax reforms alone won’t deliver the $1 trillion target. Nigeria must also strengthen manufacturing, agricultural processing, mineral development, and other productive sectors. Reliable electricity, efficient transportation, affordable financing, and predictable regulation are equally critical.
In short, a tax policy that encourages investment must be matched by an environment where investment can actually deliver returns.
The minister also underscored the roles of fintech, insurance, trade, and the capital market. Digital financial services can lower transaction costs and widen access to finance. Insurance can protect businesses and households while mobilizing long-term investment funds. Trade facilitation and export development can help Nigerian businesses reach larger markets across Africa and beyond.
He described these sectors as interconnected: investment expands production, production creates jobs, employment raises incomes, technology improves efficiency, insurance protects assets, and trade opens new markets.
The capital market, too, has a key role in mobilizing funds for businesses, infrastructure, and other productive activities.
The Media’s Responsibility
Oyedele called on FiBOP and the wider media to help Nigerians understand the goals and implications of economic reforms. He urged journalists to distinguish verified data from speculation and clearly separate proposed policies from implemented ones.
But he also said government must provide timely information, explain its decisions, and welcome constructive scrutiny.
“Public confidence is strengthened when citizens understand not only what government is doing but why it matters and how progress will be measured,” he said.
Ultimately, Nigeria’s $1 trillion ambition will require more than policy announcements and revenue targets. It will depend on sustained investment, infrastructure, access to finance, productive enterprises, and consistency in government policy.
For Oyedele, success means whether these efforts improve productivity, create jobs, strengthen businesses, and raise living standards.
The challenge is ensuring economic growth translates into tangible benefits for Nigerians. If the new tax policy encourages investment and expands productive activity without burdening ordinary citizens and businesses, it could become a powerful tool in Nigeria’s journey to a $1 trillion economy by 2030.